
Key Takeaways
-
Years of underinvestment and lengthy development timelines constrain new supply, supporting the case for a potential commodity supercycle.
-
Energy and materials account for less than 6% of the S&P 500, leaving broad equity portfolios with limited exposure to commodity-related businesses.1
-
Persistent inflation strengthens the case for revisiting commodity exposure and its role in portfolio diversification.
The world’s major growth themes require more energy, metals, and infrastructure. AI needs power and cooling. Electrification requires copper and aluminum. New factories and defense systems depend on industrial materials. Yet investors tracking broad equity indexes may have surprisingly little exposure to the businesses supplying these essential inputs.
We believe that disconnect deserves attention. With supply slow to respond and inflation proving persistent, commodities warrant a more deliberate place in the investment conversation.
Equity Benchmarks Are Light on Commodities
As we noted earlier this year, S&P 500 concentration remains historically elevated, with a heavy technology tilt. Energy represents less than 4% and materials less than 2% of the index¹—roughly one-third to one-half their baseline over the past three decades.
Energy and Materials Represent Less Than 6% of the S&P 500
S&P 500 sector weights (%), 1996–2026
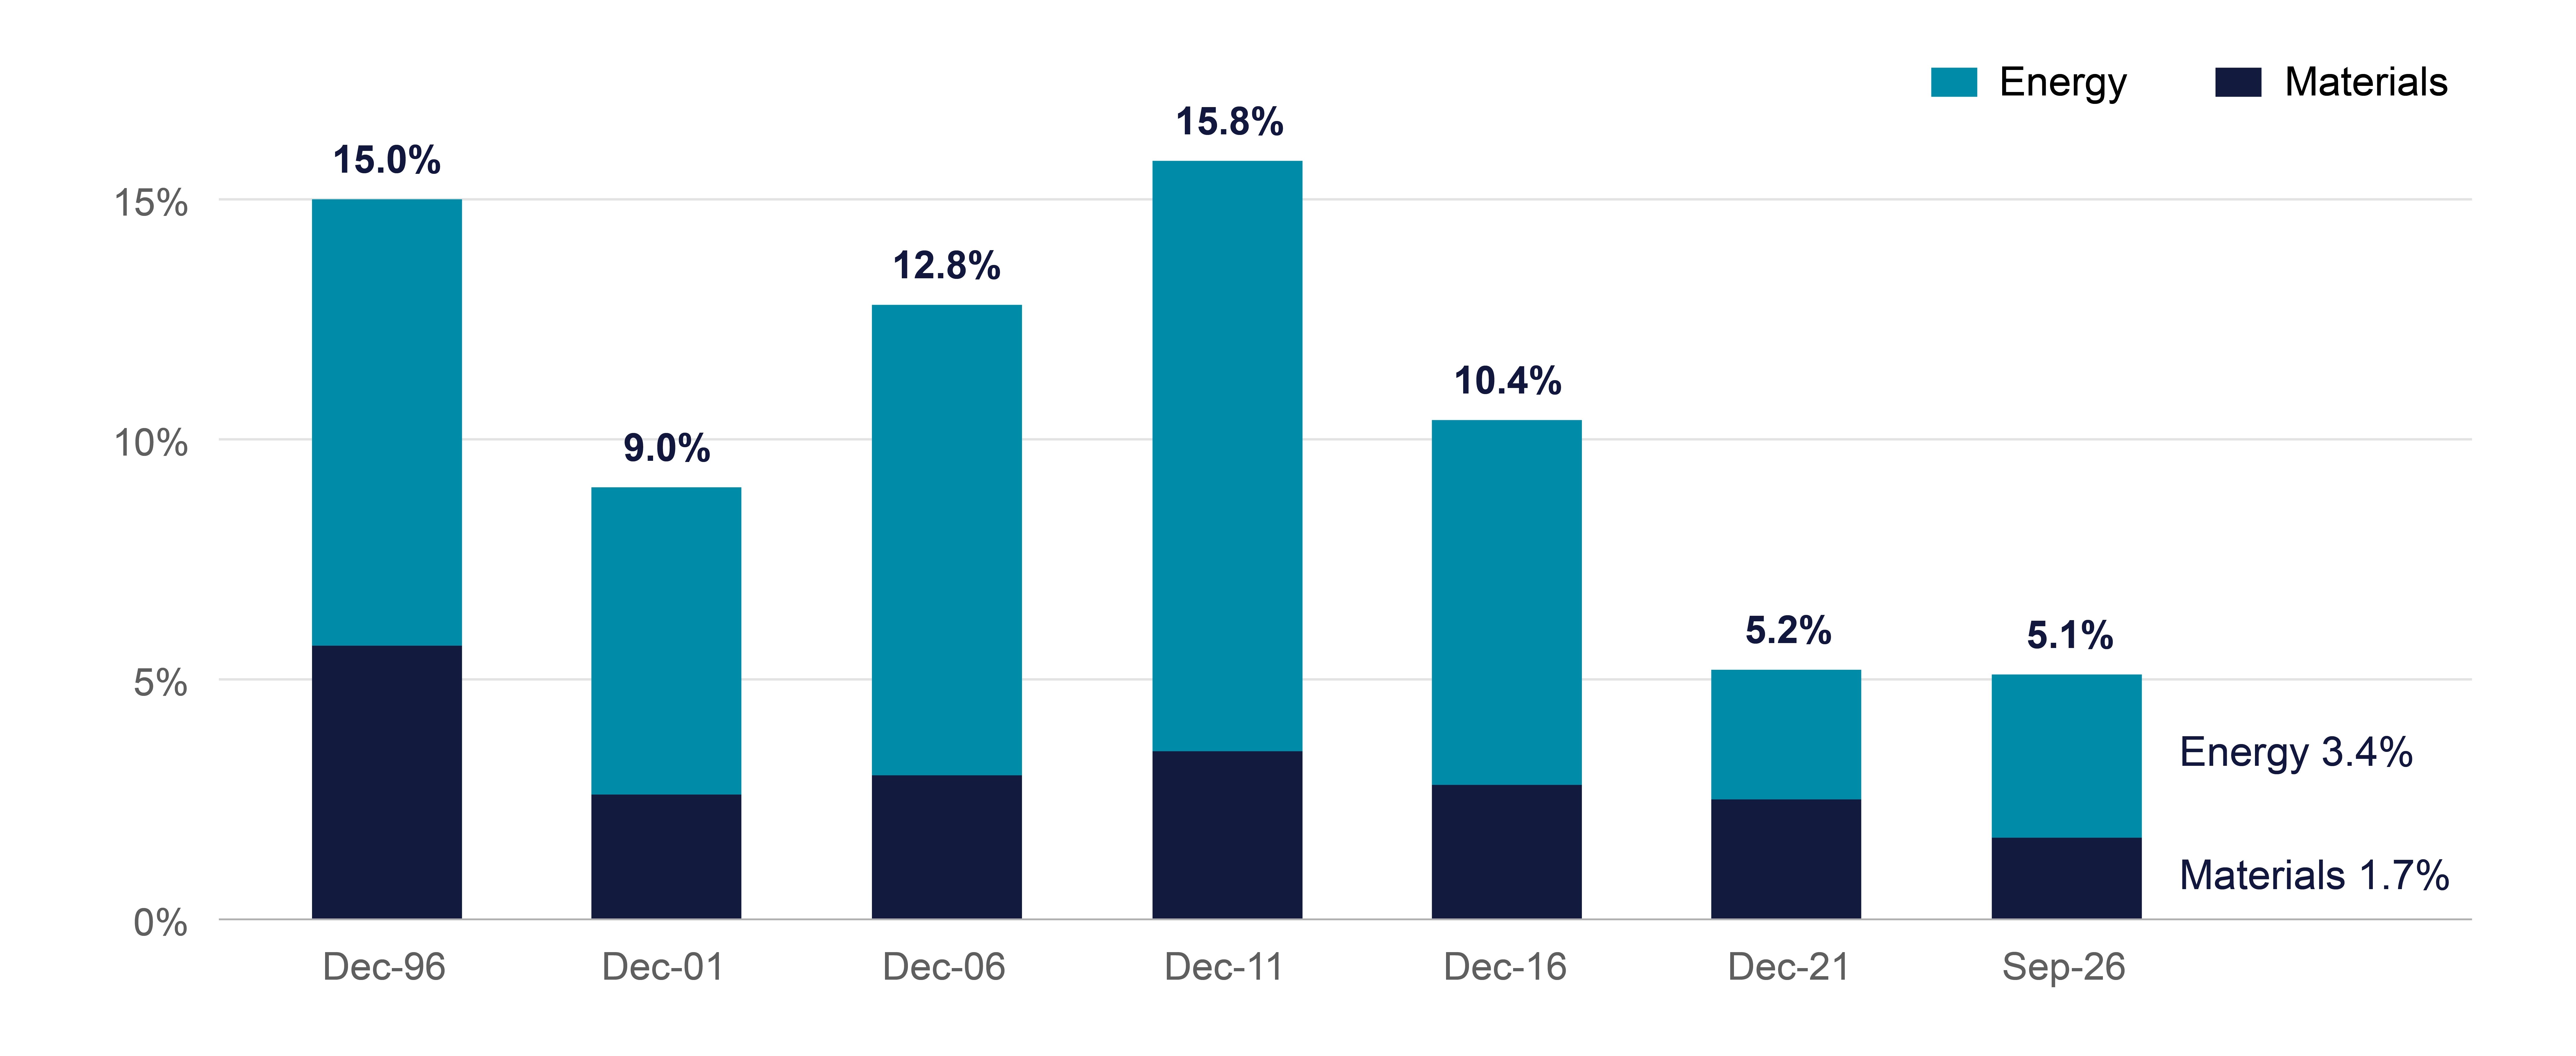
Sources: Bespoke Investment Group. Year-end weights through 2021. 2026 weights as of Sep 30; Bloomberg, Sep 2026.1
Sector weights do not capture the entire story. They do, however, show why investors should examine what exposure their equity benchmarks actually provide.
Megatrends Need Physical Inputs
Commodity demand connects many of the themes already attracting investor capital. Copper and aluminum carry electricity through power networks and equipment. Lithium, nickel, and graphite support battery production. Defense and industrial investment require metals for aircraft, vehicles, factories, and machinery.2
For investors, these shared inputs broaden the opportunity. A company supplying copper or essential infrastructure may serve several growing end markets. Its prospects can depend on the scale of investment across those markets, alongside its costs, asset quality, and capital discipline.
Megatrends Are Driving Structural Commodity Demand
Selected commodity inputs across AI, electrification, batteries, defense, and industry
Source: U.S. Geological Survey, Feb 2026.2
Supply Takes Years to Respond
Rising demand does not immediately produce new supply. S&P Global estimates that mines entering production in 2020-2024 took an average of 17.8 years to develop, nearly three times the lead time for mines that began operating in the 1990s. Exploration, permitting, and financing account for much of the delay.3
That mismatch is central to the potential for a commodity supercycle, a prolonged period in which demand growth outpaces the industry’s ability to expand supply. We see the possibility of a sustained investment cycle, with opportunities for both resource producers and the companies that build, equip, and connect their operations.
The historical commodity upswings shown below lasted roughly nine years on average.⁴ If the cycle that began in 2021 follows a similar pattern, it could have another three to four years to run, depending on how supply and demand evolve.
Commodity Supercycles Can Span a Decade
Commodity futures total returns (indexed to 100), 1900–2025
 Source: SummerHaven Index Management May 2026.4 Notes: Equal-weighted commodity futures baskets, indexed to 100. Composition varies over time.
Persistent Inflation Adds Urgency
Inflation also gives investors a reason to reconsider their exposure. The Fed projects inflation (Core PCE) of 3.4% in 2026, 2.5% in 2027, and 2.2% in 2028—remaining above its 2% target throughout that period.⁵ This persistence strengthens the case for commodities and other real assets with tangible economic value. An ounce of gold, for example, can serve as a store of wealth as inflation erodes the purchasing power of money.
Higher commodity prices can also support producer revenues, giving resource companies a potential tailwind from the same price pressures that raise costs elsewhere in the economy.
Real Assets Have Excelled in High Inflation
Average annual returns by U.S. inflation regime (%), 1970–2025
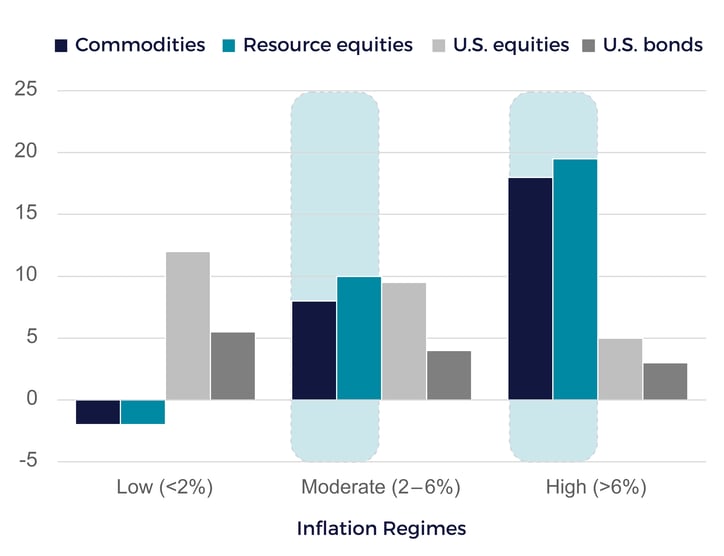
Sources: VanEck, Bloomberg, CRSP, and FactSet, Sep 2026.6
Why It Matters
Commodities can play a distinct role in portfolios, offering diversification, a potential hedge against inflation, and exposure to real assets. Broad equity indexes provide limited exposure to the businesses producing and supporting these resources. We believe the combination of historically high S&P 500 concentration and persistent inflation strengthens the case for commodities today.
Commodities Can Improve Portfolio Diversification
3-year asset correlations through Sep 30, 20267
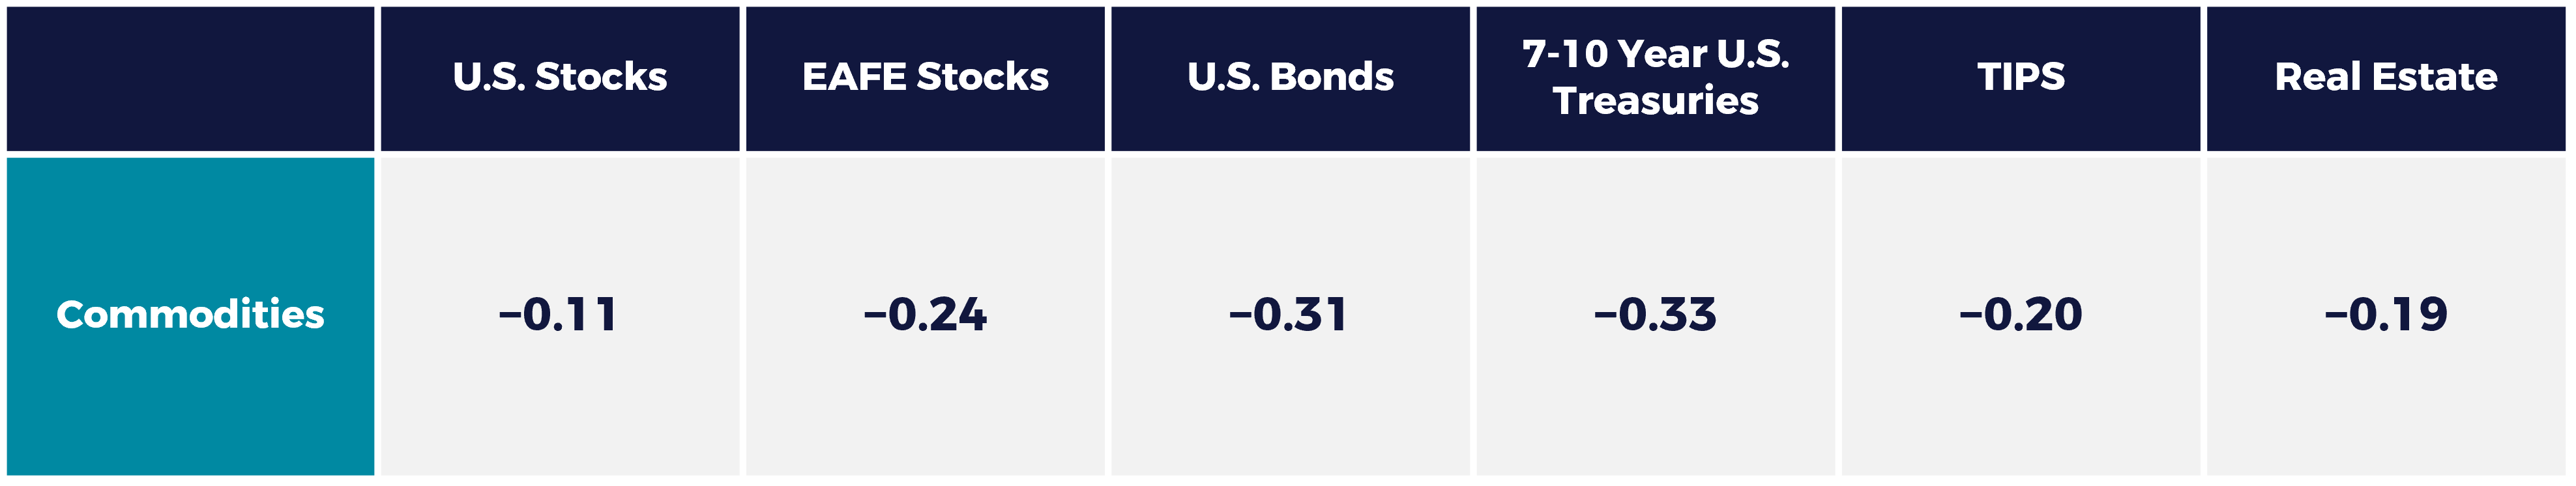
Notes: Proxies used are DBIQ for Commodities, SPX for U.S. stocks, MSCI World ex USA IMI for EAFE stocks, LCO8TRUU for U.S. bonds, GATS for 7–10-year U.S. Treasuries, and MSCI US Investable Market Real Estate 25/50 Index for real estate. TIPS refers to Treasury Inflation-Protected Securities.
How to Access the Opportunity
Investors have long accessed commodities through mutual funds and ETFs, including strategies that hold physical commodities or use futures. Those approaches come with structural trade-offs. Futures returns can diverge from spot prices as contracts are rolled, while some commodity funds issue Schedule K-1s that add considerable tax-reporting complexity.
Commodity equities offer another route through the businesses producing resources and those supporting their production, movement, and trade. Our two strategies provide distinct solutions:
- Tema Commodity Income ETF (ICOM) targets income alongside commodity upside by investing in dividend-paying businesses across energy, precious and base metals, and agriculture.
- Tema Commodity Infrastructure ETF (THRU) invests across the infrastructure that keeps commodities moving, including energy infrastructure, mining services, logistics, exchanges, and trading houses, with an emphasis on durable cash flows.